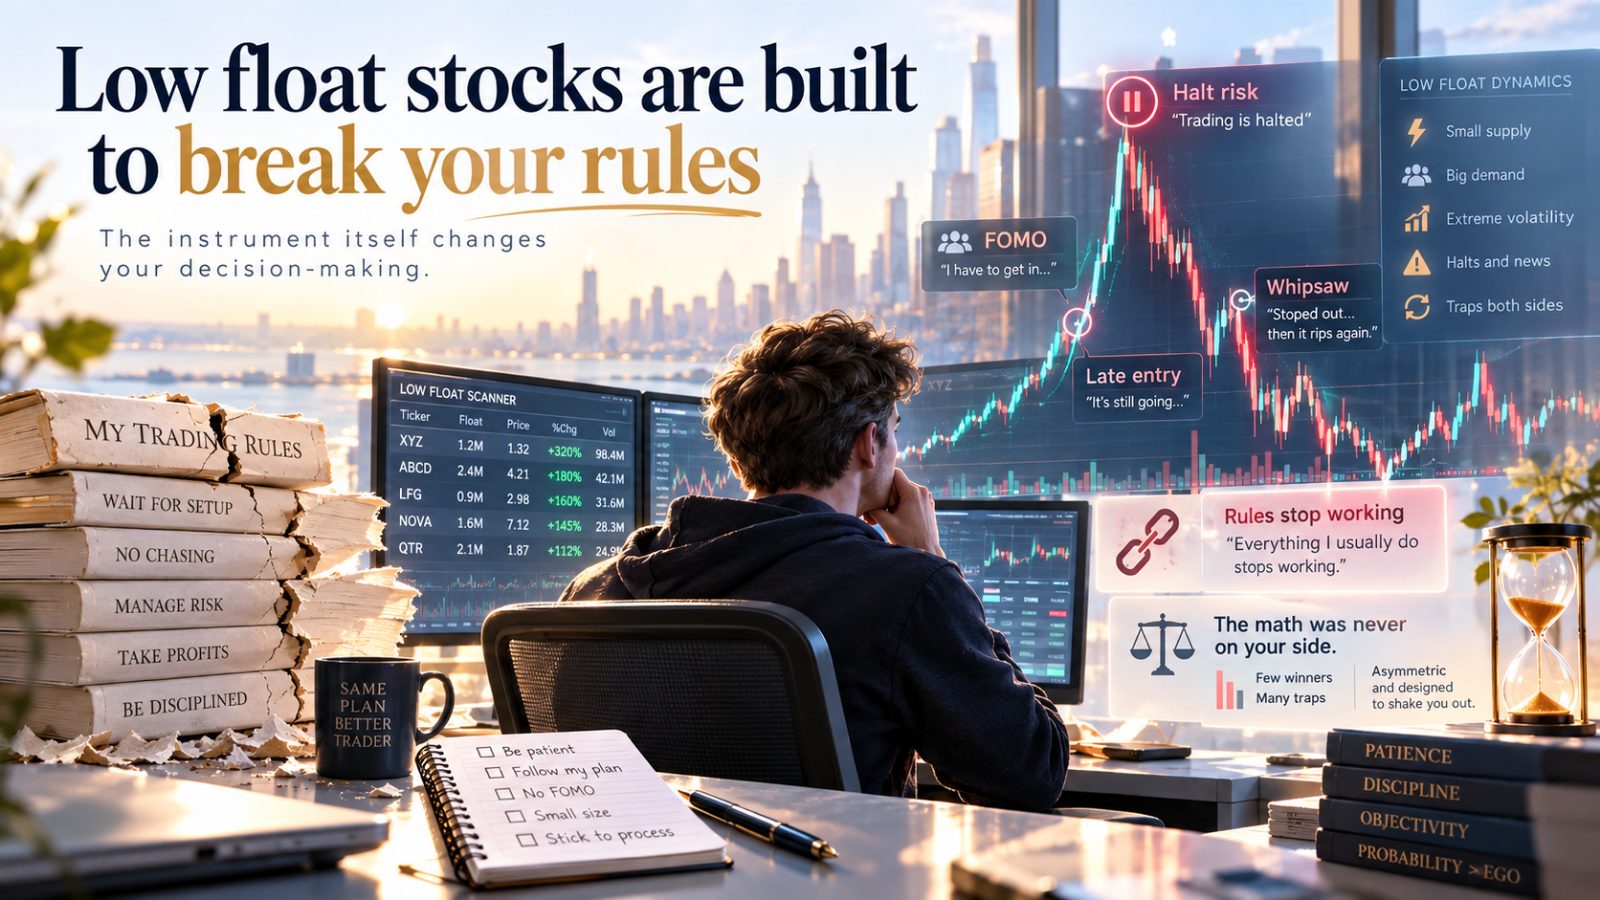
Nobody who has ever blown up on a low float stock will tell you the setup was bad. They'll tell you they got in late. They'll tell you the halt caught them wrong-sided. They'll tell you they should have taken the first push. What they won't say — because it sounds like an excuse — is that the stock itself was built in a way that made their normal rules stop working.
That part is actually true. And it's worth saying out loud before the next one shows up on your scanner at the open.
THE MECHANIC
Thin supply is a different animal, not a faster one
You already know what float is. Shares available to actually trade, after you back out insiders and locked holders. You've seen the 3M-float runners. You've traded them. The thing worth saying is not what float is but what thin float does to the auction.
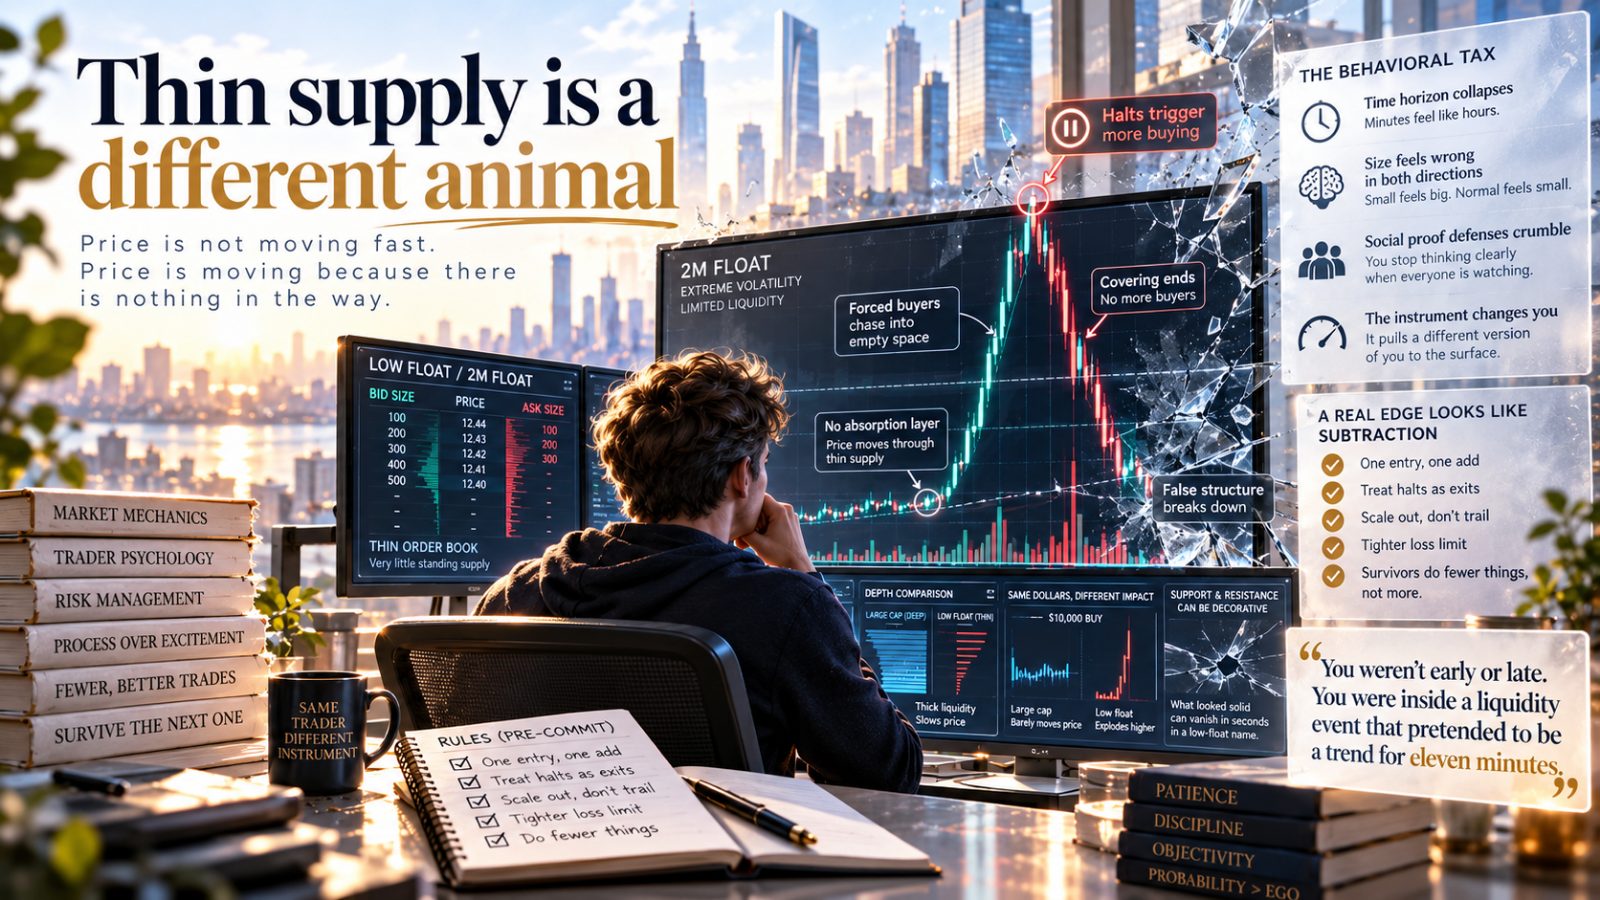
On a normal-cap name, buyers and sellers at any price are deep enough that one aggressive order gets absorbed. On a 2M-float name with real catalyst volume, there is no absorption layer. A single institutional buy, a single short cover, a single retail panic-chase moves price through multiple levels before the book repopulates. Price is not moving fast. Price is moving because there is nothing in the way.
That distinction matters because it changes what your tools are telling you. A level that would hold on AAPL is decorative on a 1.8M-float biotech at 10:30 on halt-resume day. You're not reading structure. You're reading a corridor that happens to look like structure for the twenty seconds before it isn't.
THE SQUEEZE
A squeeze is a liquidity event, not a trade
Short interest piles up on these names because the thesis is usually easy — overextended, no earnings, dilution incoming, pick your flavor. The squeeze happens not because the shorts were wrong about the company. It happens because the shorts were right and still had to cover into a book that couldn't fill them without walking price up a dollar at a time.
Which means the trader long into the squeeze is not catching a move. They are riding a forced-buyer event with a known expiration. The moment the covering ends — and it always ends — the same thin book that walked price up walks it back down with equal violence. There is no two-sided fight at the top. There is nobody left to buy.
You weren't early or late. You were inside a liquidity event that pretended to be a trend for eleven minutes.
This is why the standard rules — trail your stop, let winners run, add on strength — mutate on these names. Trailing a stop through a book that has no bids is how a $2,400 unrealized winner becomes a $600 realized one in the time it takes to blink. The rule didn't fail you. The instrument it was written for isn't the instrument you're trading.
THE BEHAVIORAL TAX
What the instrument does to the trader
Here's the part that doesn't get written about enough. Low float stocks don't just move differently. They make you different.
Three things happen inside your head when you're sized into a 2M-float runner:
- Your time horizon collapses. A trade you'd normally give fifteen minutes to work, you're now checking every two seconds. Decision cycles compress to match the chart, not your plan.
- Your position size feels wrong in both directions. Too small when it's working. Too large when it's not. There is no sizing that feels correct in real time because the volatility outruns your sense of proportion.
- Your social proof defenses crumble. The chat is going. Twitter is going. The halt is coming. You start making decisions to not miss, instead of decisions to be right.
None of that is a character flaw. It's what thin supply does to a nervous system that evolved to notice sudden motion. The instrument is doing something to you before you've placed the trade. If you don't name that out loud, you'll keep thinking you have a discipline problem on these names when what you actually have is a sensory-overload problem that discipline alone can't fix.
THE ACTUAL EDGE
The traders who survive these names do fewer things, not more
Watch anyone who has traded low float runners for more than two years consistently. They are not doing something you aren't doing. They are refusing to do five things you are doing.
- They size for the instrument, not the setup. Half of what they'd take on a normal name. Sometimes a quarter.
- They pre-commit to one entry and one add. Not three, not "if it holds VWAP I'll scale." One and one. Decisions made before the stock opened.
- They treat halts as exits, not as pauses. The resume is a different trade, with different information, and it gets re-evaluated from zero.
- They don't trail. They scale out at pre-planned levels and let the last runner go on a hard stop they wrote down before the first fill.
- They know their session loss limit on these names specifically, and it is tighter than their normal day's limit because the instrument is tighter.
Notice none of that is about reading the chart better. The chart is the same chart. The edge is almost entirely in what gets subtracted from the trader's behavior before the bell.
Where this leaves you tomorrow
Low float stocks are not going away. The catalysts that create them — small biotechs, tiny-cap reverse splits, meme-adjacent squeezes — are a permanent feature of the small-cap landscape, and some of the cleanest multi-R days of your career will come from them. That's not the question.
The question is whether you have a system that recognizes which instrument you're trading and automatically adjusts the rules you're held to. Size caps that tighten when the float drops below a threshold. A loss limit that resets on halt-heavy days. A nudge when you've taken more than one entry on the same ticker inside ten minutes. A record, visible to you, of how you actually perform on sub-5M-float names versus everything else — because almost nobody tracks it, and almost everybody is worse at it than they think.
That's the thing a trader working alone cannot build for themselves in the moment. In the moment, the chart is going, and you are not auditing yourself. You are reacting. The infrastructure has to exist before the ticker shows up on the scanner, or it doesn't exist at all. MAKETZO exists for exactly that gap — the one between knowing low float breaks your rules and actually having something enforce different rules while the stock is live.